Maybe you’ve looked at your life and thought, “I don’t have enough to start anything.” Not enough savings, not enough time, not enough room in the budget. Just bills, responsibilities, and a quiet feeling that you should be further along by now.
There’s a woman in the Bible who felt the same way, and her story may be the most practical money lesson in the Old Testament. If you’ve ever wondered about the widow’s oil 2 Kings 4 meaning, here it is in one line: she was trapped by one kind of debt and set free by another kind of borrowing. God started with what she had, and then He told her to borrow what she didn’t have.
Let’s walk through it, because this isn’t just a miracle story. It’s a lesson in leverage.
The Story: A Creditor at the Door
Second Kings 4 opens with a crisis. A widow comes to the prophet Elisha. Her husband feared the Lord, but he died and left debt behind. Now the creditor is coming for her two sons.
“…the creditor is come to take unto him my two sons to be bondmen.” (2 Kings 4:1, KJV)
Let that sink in. This family wasn’t about to lose a house or a car. They were about to lose their children. In the ancient world, unpaid debt could turn a free family into a bound one.
Elisha doesn’t take up an offering. He doesn’t call the creditor. He asks a question:
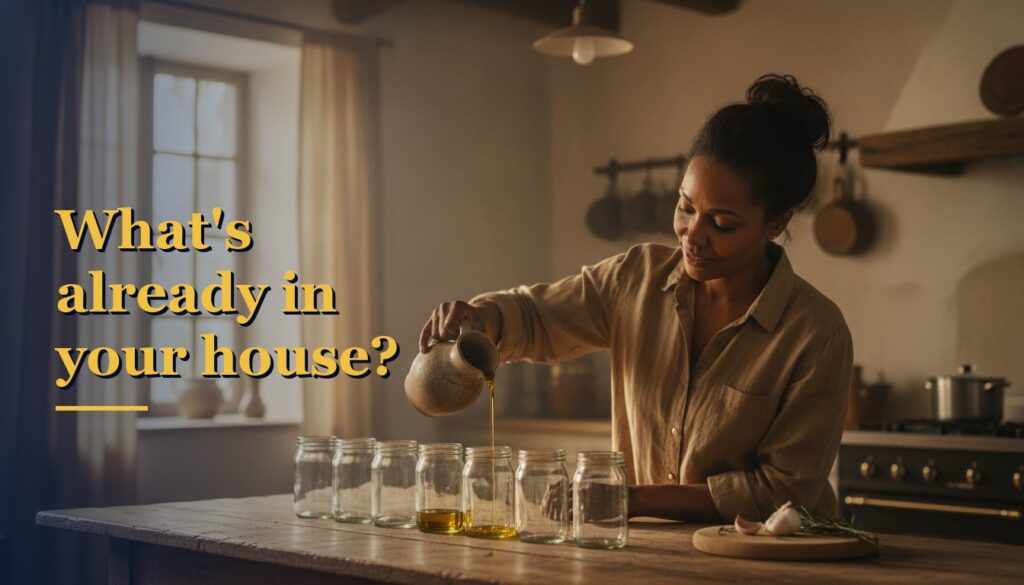
“What shall I do for thee? tell me, what hast thou in the house?” (2 Kings 4:2, KJV)
Her answer is one many of us would give: “Thine handmaid hath not any thing in the house, save a pot of oil.”
Nothing, except. That “except” changed everything.
“Borrow Not a Few”: The Leverage in 2 Kings 4
Here’s the part most sermons rush past. Elisha’s very next instruction is to borrow:
“Go, borrow thee vessels abroad of all thy neighbours, even empty vessels; borrow not a few.” (2 Kings 4:3, KJV)
Let me be accurate about the text. She didn’t borrow cash. She borrowed capacity. Her neighbors’ empty jars were assets she didn’t own, and she used them to multiply the little she did own. That is the essence of leverage: using what belongs to someone else, for a season, to produce more than you could produce alone.
She shut the door with her sons and poured. The oil kept flowing until every borrowed vessel was full. When her son told her there wasn’t one more, “the oil stayed” (2 Kings 4:6, KJV). Notice what set the limit. It wasn’t the oil. It was how much she borrowed. “Borrow not a few” was an invitation to think bigger than her pot.
Then came the business plan:
“Go, sell the oil, and pay thy debt, and live thou and thy children of the rest.” (2 Kings 4:7, KJV)
Follow the sequence. She borrowed capacity. She filled it. She turned it into a product and sold it. The sales paid off the creditor who was coming for her sons. And what was left kept feeding her family after the crisis was over. I call that passive income: provision that keeps working after the emergency is gone.
Two Kinds of Debt in One House
Here’s what I don’t want you to miss. There were two kinds of borrowing in this story, and they pointed in opposite directions.
The first was the debt her husband left behind. It consumed. It produced nothing, and it was about to take her sons as payment. I call that Trash Debt: debt that consumes income. Today it looks like the car note, the credit card balance and the lifestyle financing that eat a paycheck before it arrives.
The second was the borrowing Elisha told her to do. It produced. The vessels held oil that became income, and that income was far greater than the cost of borrowing them. I call that Tool Debt: debt that produces income greater than its cost.
Same instrument, opposite direction. Borrowing nearly enslaved this family, and borrowing set them free. So the question is never “Is debt evil?” The question is, “Is this debt serving me, or am I serving it?”
In the F.R.E.E.D.O.M. Framework, this story lives in the third pillar, Escape Bondage. But look at how the widow escaped. She didn’t just cut back. She built new flow and pointed it at the debt that had her family in chains. The system runs on Slave Arithmetic: housing, transportation, taxes, debt, insurance and giving add up to nearly 100% of income before groceries. I break that down in The 100% Trap. The widow’s math ran the other way. They taught us Slave Arithmetic. We teach Owner’s Math.
Five Lessons From the Widow’s Oil
1. Start with what you have
She said she had nothing, but she had oil. Most of us overlook a skill, a certification, an experience or a relationship because it seems too small. That small thing may be your pot of oil. Leverage multiplies something. It can’t multiply nothing.
2. Borrow to produce, not to consume
She didn’t borrow to cover a lifestyle. She borrowed to produce. Tool Debt always has a job to do. If you can’t name the job and the income it will produce, it isn’t a tool.
3. Your capacity limits your overflow
The oil stopped when the vessels ran out. Many of us have what looks like a flow problem that is really a capacity problem: no system, no equipment, no room to serve more people.
4. The miracle required a market
God didn’t fill her house with coins. He filled it with a product, and she still had to sell it. God provided the supply. She provided the business.
5. Pay the Trash Debt, then live on the rest
The order matters. The business paid off the debt that threatened her sons, and then it kept providing. The rescue became a livelihood.
The Worked Numbers: Your Pot of Oil, Leveraged
Let’s make this practical with a composite example. Picture a nurse, we’ll call her Angela, earning $85,000 a year with $9,000 on credit cards. She’s certified to teach CPR and first aid. That’s her pot of oil.
Step one: start with what she has. Using her own training equipment, she teaches two weekend classes a month for parents, churches and small businesses:
- 2 classes × 10 students × $60 = $1,200 a month.
- She sets aside about 25% for taxes and supplies: $300.
- That leaves $900 a month for the cards: $9,000 ÷ $900 = about 10 months, a little longer once interest is counted.
Step two: borrow vessels. The classes keep filling up and she’s turning people away. Her limit isn’t demand. It’s capacity. So she borrows some. Her church lends her its fellowship hall, and she takes a $3,000 equipment loan for more training manikins, repaid over 12 months at about $264 a month.
- 2 classes × 20 students × $60 = $2,400 a month.
- Set aside 25%: $600. That leaves $1,800.
- Minus the equipment loan: $1,800 − $264 = $1,536 a month for the cards.
- $9,000 ÷ $1,536 = about 6 months instead of 10.
That $3,000 loan passes the test. It costs about $264 a month and helps produce an extra $1,200 a month in revenue. It’s Tool Debt. And once the cards are gone and the equipment is paid off, she has roughly $1,800 a month of ongoing flow, or $1,800 × 12 = $21,600 a year, to build savings and buy assets. That’s “live thou and thy children of the rest.”
Now the guardrail. If the classes stopped filling, Angela would still owe that $264 every month. So before she borrowed, she proved demand with what she already had, and she kept a few months of the payment in a separate reserve. Tool Debt needs an asset, a plan to repay, and cash on hand in case the asset stops producing. Side income also carries tax responsibilities, so talk with a qualified tax professional to set it up correctly from day one.
Finding Your Pot of Oil and Your Vessels
If you’re thinking, “George, I still don’t have anything,” let me ask you Elisha’s question: what do you have in the house?
- What do people already ask you for help with? Resumes, hair, taxes, cooking, fixing cars, planning events?
- What do you do at work that people outside your company would pay for?
- What certifications, licenses or training do you already have?
Then ask the leverage question: whose vessels could you borrow? A church kitchen on a weekday. A friend’s storefront after hours. A mentor’s audience. Equipment you finance only after you’ve proven people will pay. The widow didn’t do this alone. Her neighbors’ empty jars became her capacity.
And don’t despise the small beginning. Her miracle started with one pour from one jar. Your first month might bring in $200, not $1,200. That’s still proof that the oil flows, and proof is what makes the next vessel worth borrowing.
Your Next Move
Here are five steps you can take this week:
- Answer Elisha’s question on paper. Write down ten things you know how to do, have access to, or have experienced.
- Circle one pot of oil. Pick the one people would most readily pay for, and find your first three customers.
- Sort your debts into two columns. Trash Debt (consumes income) and Tool Debt (produces more than it costs). Be honest about which column each one belongs in.
- Name the vessel you’d borrow. What capacity would let you serve twice as many people? Write down what it costs and what it would need to produce to pass the test.
- Point your first profits at the Trash Debt. Choose the specific balance your new flow will pay off first.
What’s in your house?
Take the free Freedom Quiz. In two minutes you’ll have your first move, and a front-row seat to what school never taught: how money multiplies, how passive income is built, and the money rules wealthy families pass down.
The widow walked into Elisha’s presence as a woman about to lose her sons to debt. She walked out as a business owner who knew how to borrow the right way, with the creditor paid and income to live on. That’s who you’re becoming: not someone afraid of debt, but someone who makes it serve.
You have more in the house than you think. Borrow the vessels. Start pouring.
— George M. Howard Jr., “Financial Moses”
Founder, Be Free University
Want Be Free University to show up first in your Google results?
Responses