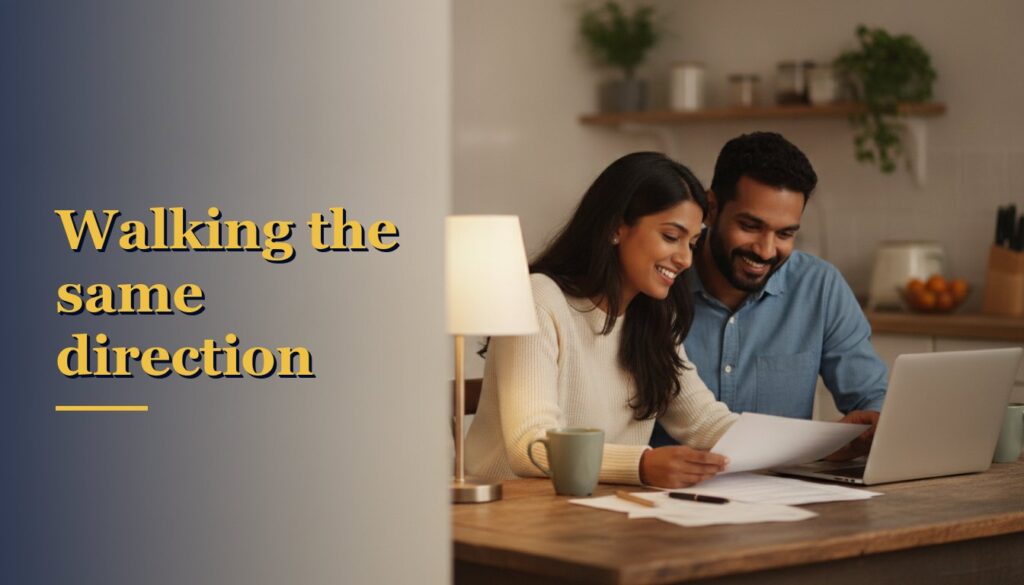
You love each other. You pray together. You both work hard. And yet the same money conversation keeps ending in silence, a slammed cabinet, or one of you quietly deciding it’s easier not to bring it up at all. If that sounds like your house, you’re living the most common pattern in Christian couples money conflict, and hear me clearly: you are not a failing marriage and you are not bad with money. You are two people trying to run one household with two different rulebooks, inside a system that never taught either of you how.
I’ve sat across the table from a lot of married folks, and the pattern is almost never about a lack of love or a lack of income. It’s about a lack of agreement. The prophet Amos asked the question that sits under every one of these arguments.
“Can two walk together, except they be agreed?” (Amos 3:3, KJV)
Two people can share a bed, a last name and a mortgage and still not be walking together. Agreement is the thing you build on purpose. Let me show you how.
Why Christian Couples Money Talks Go Sideways
Most couples don’t fight about money. They fight about what money means. To one of you, a healthy savings balance means safety. To the other, it means a missed life while you wait for “someday.” One of you grew up in a home where bills were paid on time and nobody talked about them. The other grew up in a home where money was the argument. You each walked down the aisle carrying a money story you didn’t choose.
Then the system piles on. Two incomes feel like plenty until you add them up against the real bills. Housing, two car notes, insurance, taxes, childcare, student loans, giving. By the time the math settles, there’s very little left, and each of you secretly suspects the other one is the leak. The truth is usually simpler: the math was never designed to work, and you’ve been blaming each other for a problem neither of you created. I break down that math in The 100% Trap.
Scripture calls marriage a union, not a merger of two separate budgets.
“Therefore shall a man leave his father and his mother, and shall cleave unto his wife: and they shall be one flesh.” (Genesis 2:24, KJV)
One flesh doesn’t mean one of you makes every decision. It means you stop keeping score and start building the same thing.
The Three Money Personalities in Most Marriages
You don’t need a personality test to see this. Most spouses lean toward one of three patterns, and most marriages pair two different ones.
- The Protector. Feels peace when there’s a cushion. Hates surprises. Can come across as controlling or tight.
- The Provider-Enjoyer. Works hard and wants the family to feel it: trips, dinners, gifts. Can come across as careless.
- The Avoider. Loves the family, trusts the spouse, and would honestly rather not look. Can leave the other spouse carrying the whole weight alone.
None of these is the villain. Each one holds a piece of wisdom. The Protector is right that margin matters. The Provider-Enjoyer is right that life is meant to be lived. Even the Avoider is right that money shouldn’t consume every conversation. The breakthrough comes when you stop trying to convert your spouse and start drawing on both strengths.
“Two are better than one, because they have a good return for their labor.” (Ecclesiastes 4:9, NIV)
A good return on your labor. That’s not just a poetic line. That’s a business principle sitting in the wisdom books. Two people who agree can build more, faster, than two people pulling in opposite directions.
Worked Numbers: What Disagreement Actually Costs
Let’s make this concrete. Picture a composite couple, Marcus and Dana. Together they earn $118,000 a year. After taxes, retirement contributions and insurance come out, they bring home about $7,400 a month. They’re faithful givers. They’re not reckless. But they’ve never sat down and agreed on a plan, so each of them spends “a little” on their own without telling the other.
Here’s what “a little” looks like when you add it up:
- Marcus: supplements, gaming, lunches out, about $260 a month
- Dana: online orders, coffee runs, kids’ extras she doesn’t mention, about $310 a month
- Duplicate or forgotten subscriptions nobody owns: about $85 a month
That’s $655 a month of spending neither of them fully sees. $655 × 12 months = $7,860 a year. Over five years, $7,860 × 5 = $39,300. That’s not a character problem. That’s a down payment on a rental property, or a fully funded emergency cushion with room left over, leaking out through the gap between two people who love each other but aren’t talking.
Now watch what agreement does. Suppose they sit down together and agree to give each spouse $150 a month of no-questions-asked money. That’s $300 total. The other $355 a month gets redirected to a shared goal they both chose. $355 × 12 = $4,260 a year. $4,260 × 5 = $21,300 toward something that’s theirs, not his or hers. Nobody feels policed. Nobody feels deprived. They just stopped leaking.
Vision Before Budget: Getting on the Same Page
Here’s where most couples start in the wrong place. They open a spreadsheet and start cutting. Within twenty minutes somebody feels judged and the meeting is over. Cutting without a shared vision feels like punishment. Cutting toward a shared vision feels like building.
So start with the destination. Ask each other questions like these, and actually write the answers down:
- If money weren’t the issue, what would our life look like in ten years?
- What do we want the next generation in our family to inherit from us beyond money?
- What’s one thing we’re tired of worrying about?
- What does “free” mean to each of us?
That last one matters most. For one of you, freedom might mean owing nobody. For the other, it might mean being able to leave a job you’ve outgrown. At Be Free University we teach that freedom isn’t retirement at 65. It’s passive income greater than active income. When a couple locks onto that picture together, every small decision starts pointing the same direction. I unpack that idea more in Freedom Is Not Retirement at 65.
This is the first work of Release Your Flow, the cash flow pillar of our F.R.E.E.D.O.M. Framework: before you can direct your money, the two people directing it have to agree where it’s going.
The Weekly Money Meeting That Protects Your Marriage
Agreement isn’t a one-time conversation. It’s a rhythm. The couples I’ve seen get unstuck almost always have one thing in common: a short, regular, scheduled money meeting. Not a crisis meeting. A standing appointment.
Here’s a simple format that keeps it under thirty minutes:
- Open with prayer and one win. Start by naming something that went right. It sets the tone.
- Look at the numbers together. What came in, what went out, and what’s coming up in the next two weeks. Same screen, same page, no one “presenting” to the other.
- Make one decision. Not ten. One. Cancel a subscription, move money to savings, schedule a call about the car loan.
- Close with the vision. Remind each other what you’re building and why.
A few ground rules make it work. No blame language. No bringing up old purchases to win a new argument. And no purchase over a set amount, say $200, without both of you agreeing. That one rule alone removes most of the surprises that damage trust.
“Though one may be overpowered, two can defend themselves. A cord of three strands is not quickly broken.” (Ecclesiastes 4:12, NIV)
Husband, wife and God at the center. That’s the cord. A money meeting is just a practical way to keep all three strands in the room.
Yours, Mine and Ours: Handling the Accounts
Couples often ask me whether they should combine every account. My honest answer: the account structure matters less than the agreement behind it. Some couples do beautifully with one joint account for everything. Others do better with a joint account for shared bills and goals, plus a small personal account each. What doesn’t work is secrecy.
A structure that works well for many families:
- Joint household account: both paychecks land here. All shared bills and giving come out of here.
- Joint freedom account: automatic transfers for savings and your shared goal. You don’t touch it for everyday spending.
- Two personal accounts: each spouse’s agreed no-questions money. Spend it, save it, surprise each other with it.
Whatever you choose, both of you should be able to see every balance and every debt. Full visibility isn’t about control. It’s about honor. If something happened to one of you tomorrow, the other should know exactly where everything stands.
Your next move
Don’t try to fix everything this week. Just start walking in the same direction.
- Put a 30-minute money meeting on the calendar for this week, and treat it like an appointment you’d never miss.
- Each write down your answer to “What does free mean to me?” Read them to each other without debating.
- Pull the last 60 days of bank and card statements together and total the spending neither of you fully tracked.
- Agree on a personal no-questions amount for each of you, and an amount above which you’ll always decide together.
- Choose one shared goal and set up one automatic transfer toward it, even a small one.
Are you two looking at the same numbers?
Take the free Freedom Quiz together. In two minutes you’ll have your first move, and a front-row seat to what school never taught: how money multiplies, how passive income is built, and the money rules wealthy families pass down.
When a husband and wife agree, they stop serving the system and start building something that will outlast them both. That’s the marriage God had in mind: two walking together, one direction, toward freedom.
— George M. Howard Jr., “Financial Moses”
Founder, Be Free University
Want Be Free University to show up first in your Google results?
Responses